All Categories
Featured


Medicare Part D Enrollment Guide
Nationwide likewise offers you the capability to essentially buy additional upside possible with their "High-Cap" or "High-Par" Indexed Universal Life insurance coverage financial investment techniques, which include an additional 1%-2% charge. Although this decreases an IUL's floor listed below 0%, there may be years when you desire the additional advantage potential. Varied Set of IUL Crediting StrategiesUnique Multi-Index StrategyHistory of Treating Inforce Policyholders FairlyLarge Size, Mutuality, and Solid Financial StrengthStrong concentrate on Volatility Control IndexesGood long-lasting growth, but dull early cash valuesParticipating policy loan rate is topped to be no higher than 8% Columbus Life Insurance is the IUL arm of the well-rated insurance coverage conglomerate of Western Southern Group, which entered the IUL arms race in the middle of the last decade.
Since their only responsibility as a company is to the long-lasting responsibility of insurance policy holders, they are most likely to do right by their inforce block of company. This can be clearly seen in this screenshot we recently sent out to among our customers revealing how Columbus Life's IUL cap rates have actually steadily increased from 8.75% in December 2022 to 10% precisely one year later as rates ticked up.
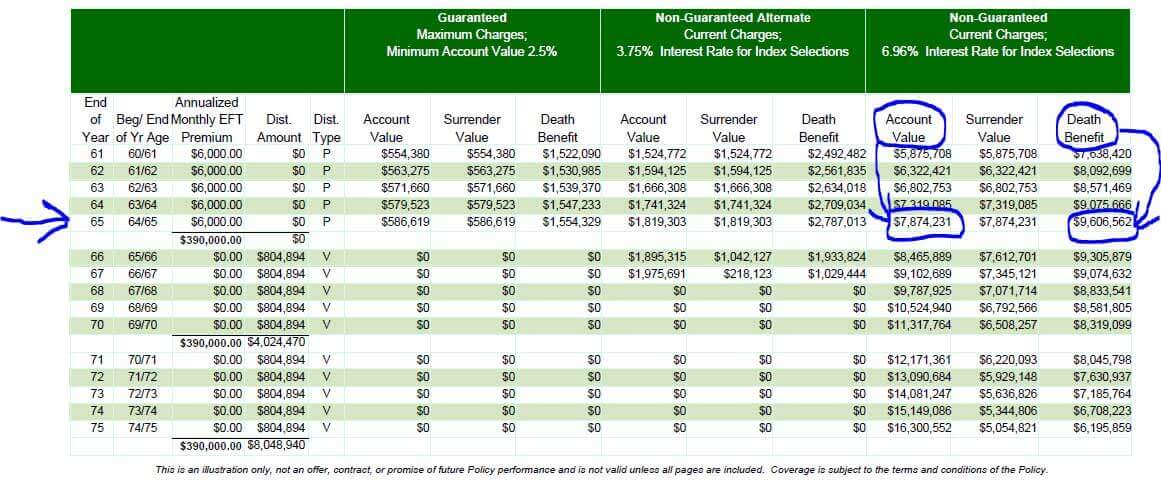
The worst IUL companies continuously claim to have the very best Indexed Universal Life insurance policy with the highest cap. Nevertheless, they'll begin with a very high cap to capture market share, then rapidly pull the rug out from under their clients once they shelve that product and start a new one.
That way, policyholders borrowing for outside financial investment chances still had the potential to make at least some favorable arbitrage. Strong S&P 500 cap rateParticipating loan rate is topped at 6% (but has been lower for a while)Their documented history of dealing with in-force insurance policy holders fairlyMutual Holding Company with no outside stockholdersTheir uncapped indexed account is currently unsightly and inactionable.
To clarify, all the best IUL companies in this post provide some sort of free persistent disease rider, but National Life Group's is perhaps the most robust. I also desire to point out that I am specifically discussing their "Peak Life" product, which is their "bigger case" product providing a more streamlined cost structure.
Final Expense Coverage Guide
Technically the rider is "complimentary", but we've discovered when stress-testing costs that the mortality expenditures are a bit higher than other of the best IUL business. This is to be expected, and you might have heard me state, "There's seldom any handle insurance. Whatever gets priced completely rather rapidly."That stated, National Life Group remains in the running for the best Indexed Universal Life insurance company for customers looking for a balance of efficiency, income, and extensive security.
Do not spend too much time on these details as your numbers will definitely differ, but this shows the kind of chronic illness rider payments they use. to discover which are presently the best IUL policies with robust Persistent Illness Riders and solid IUL crediting strategies for tax-free earnings if you do not end up being too sick or harmed to operate individually.
Indexed Universal Life Insurance coverage has so many moving parts at its core, not to point out all the potential bells and whistles various business add to their policies. If you're weighing IUL versus your existing retirement accounts, our complete breakdown of covers the crucial distinctions in contribution limits, tax treatment, and flexibility.
Throughout the majority of the 1900s the only life insurance coverage items were Whole Life and Term. Term insurance coverage provided lower expenses for short-lived life insurance protection. Whole Life supplied an ensured death advantage for a guaranteed level premium, but also had a connected savings component with an ensured long-term development rate as well as non-guaranteed dividends.
Insurance in Redondo Beach CAFinal Expense Insurance Options
The concept with Universal Life is that the development of the cost savings account will decrease the quantity of pure insurance in the policy, which would lower the increasing cost per unit of survivor benefit. In 1986, soon after the meteoric rise of Universal Life, life insurance coverage companies had the concept of including a financial investment element.
This led to the internal revenue service limiting how much premium anybody could pump into any quantity of irreversible death benefit for future tax-free retirement income. Regardless, as the stock market raved on throughout the 1990s, VUL ended up being the insurance product of option for cash accumulation. In 1997, the first Indexed Universal Life product was developed by TransAmerica (not on the list of 2026 Best IUL business). In the beginning, Indexed Universal Life insurance didn't make a huge splash at all.

Latest Posts
Medicare Part D Enrollment Guide
Choosing Between HMO and PPO Plans for Maximum Value

How Permanent Life Insurance Secures Your Financial Legacy